

Biotech Public Market Overview
Macro Theme
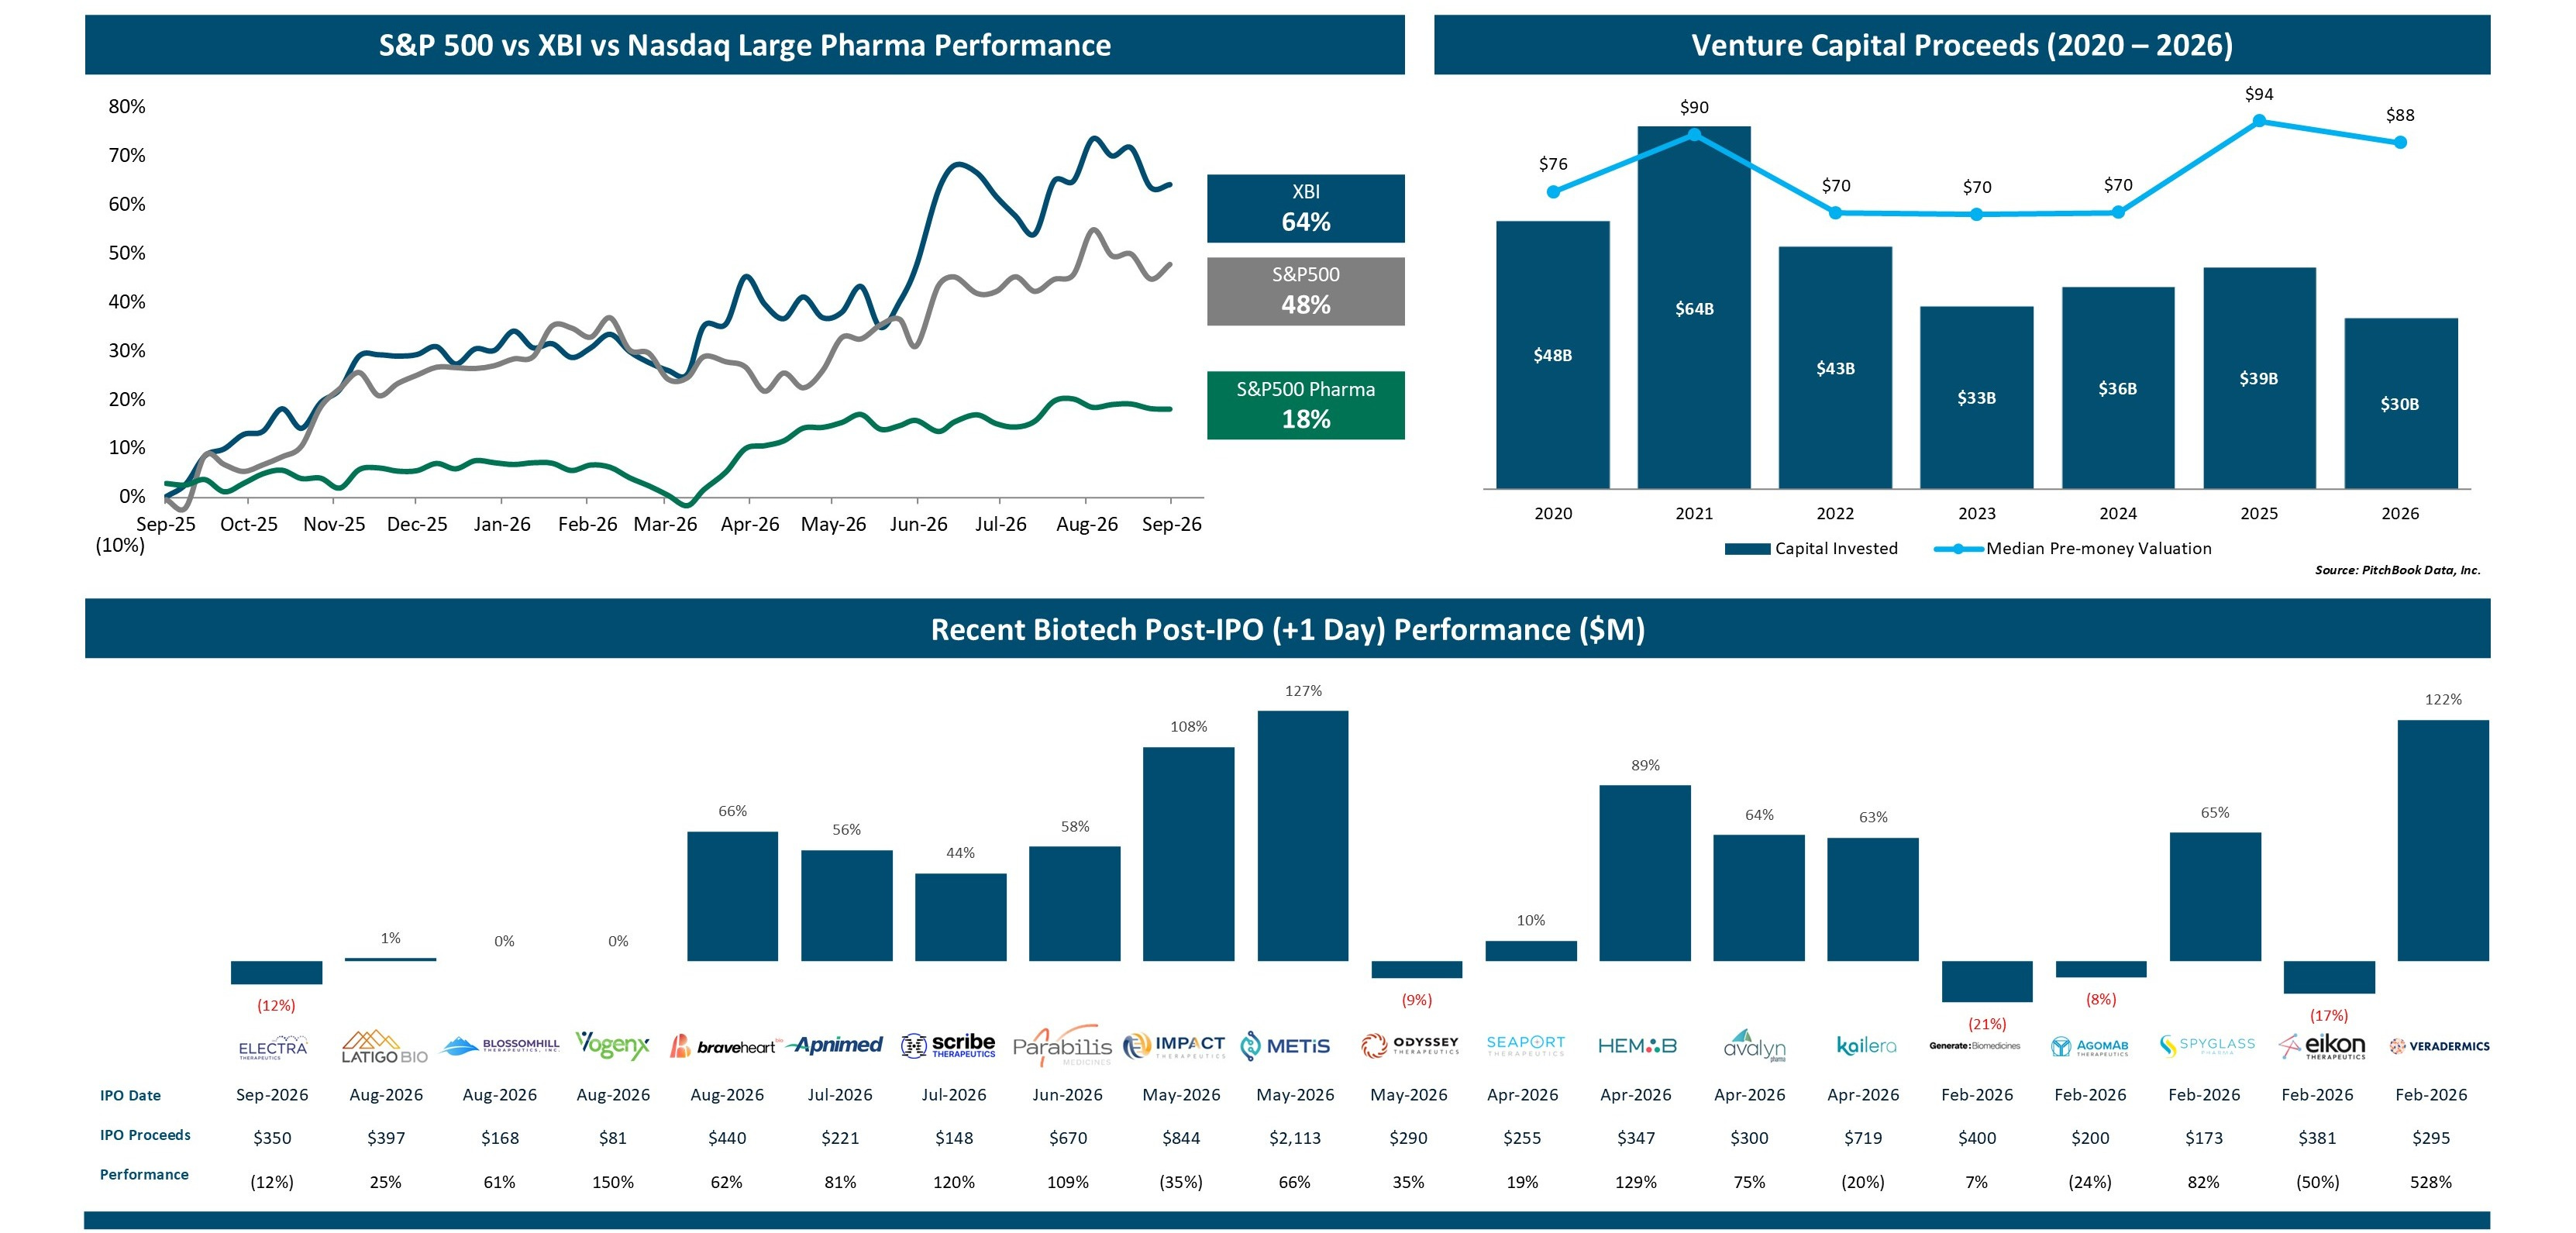
Higher rates are re-emerging as a biotech valuation headwind: Renewed inflation concerns and higher Treasury yields are increasing duration risk for development-stage biotech, with valuations vulnerable if financial conditions tighten further.
FDA / Regulatory — Leadership stabilization is reducing policy uncertainty: Recent CDER and CBER appointments are shifting attention back toward review consistency, scientific standards, and a more predictable regulatory environment.
Clinical Development — Biomarker validation is becoming a larger underwriting risk: Recent failures highlight that biomarker modulation alone is insufficient, increasing the burden of proof and potentially raising development costs where large outcomes studies are required.
Clinical Trials — Endpoint design is becoming as important as target biology: Investors are placing greater weight on validated biomarkers, assay reproducibility, and clinically meaningful endpoints before assigning value to early efficacy signals.
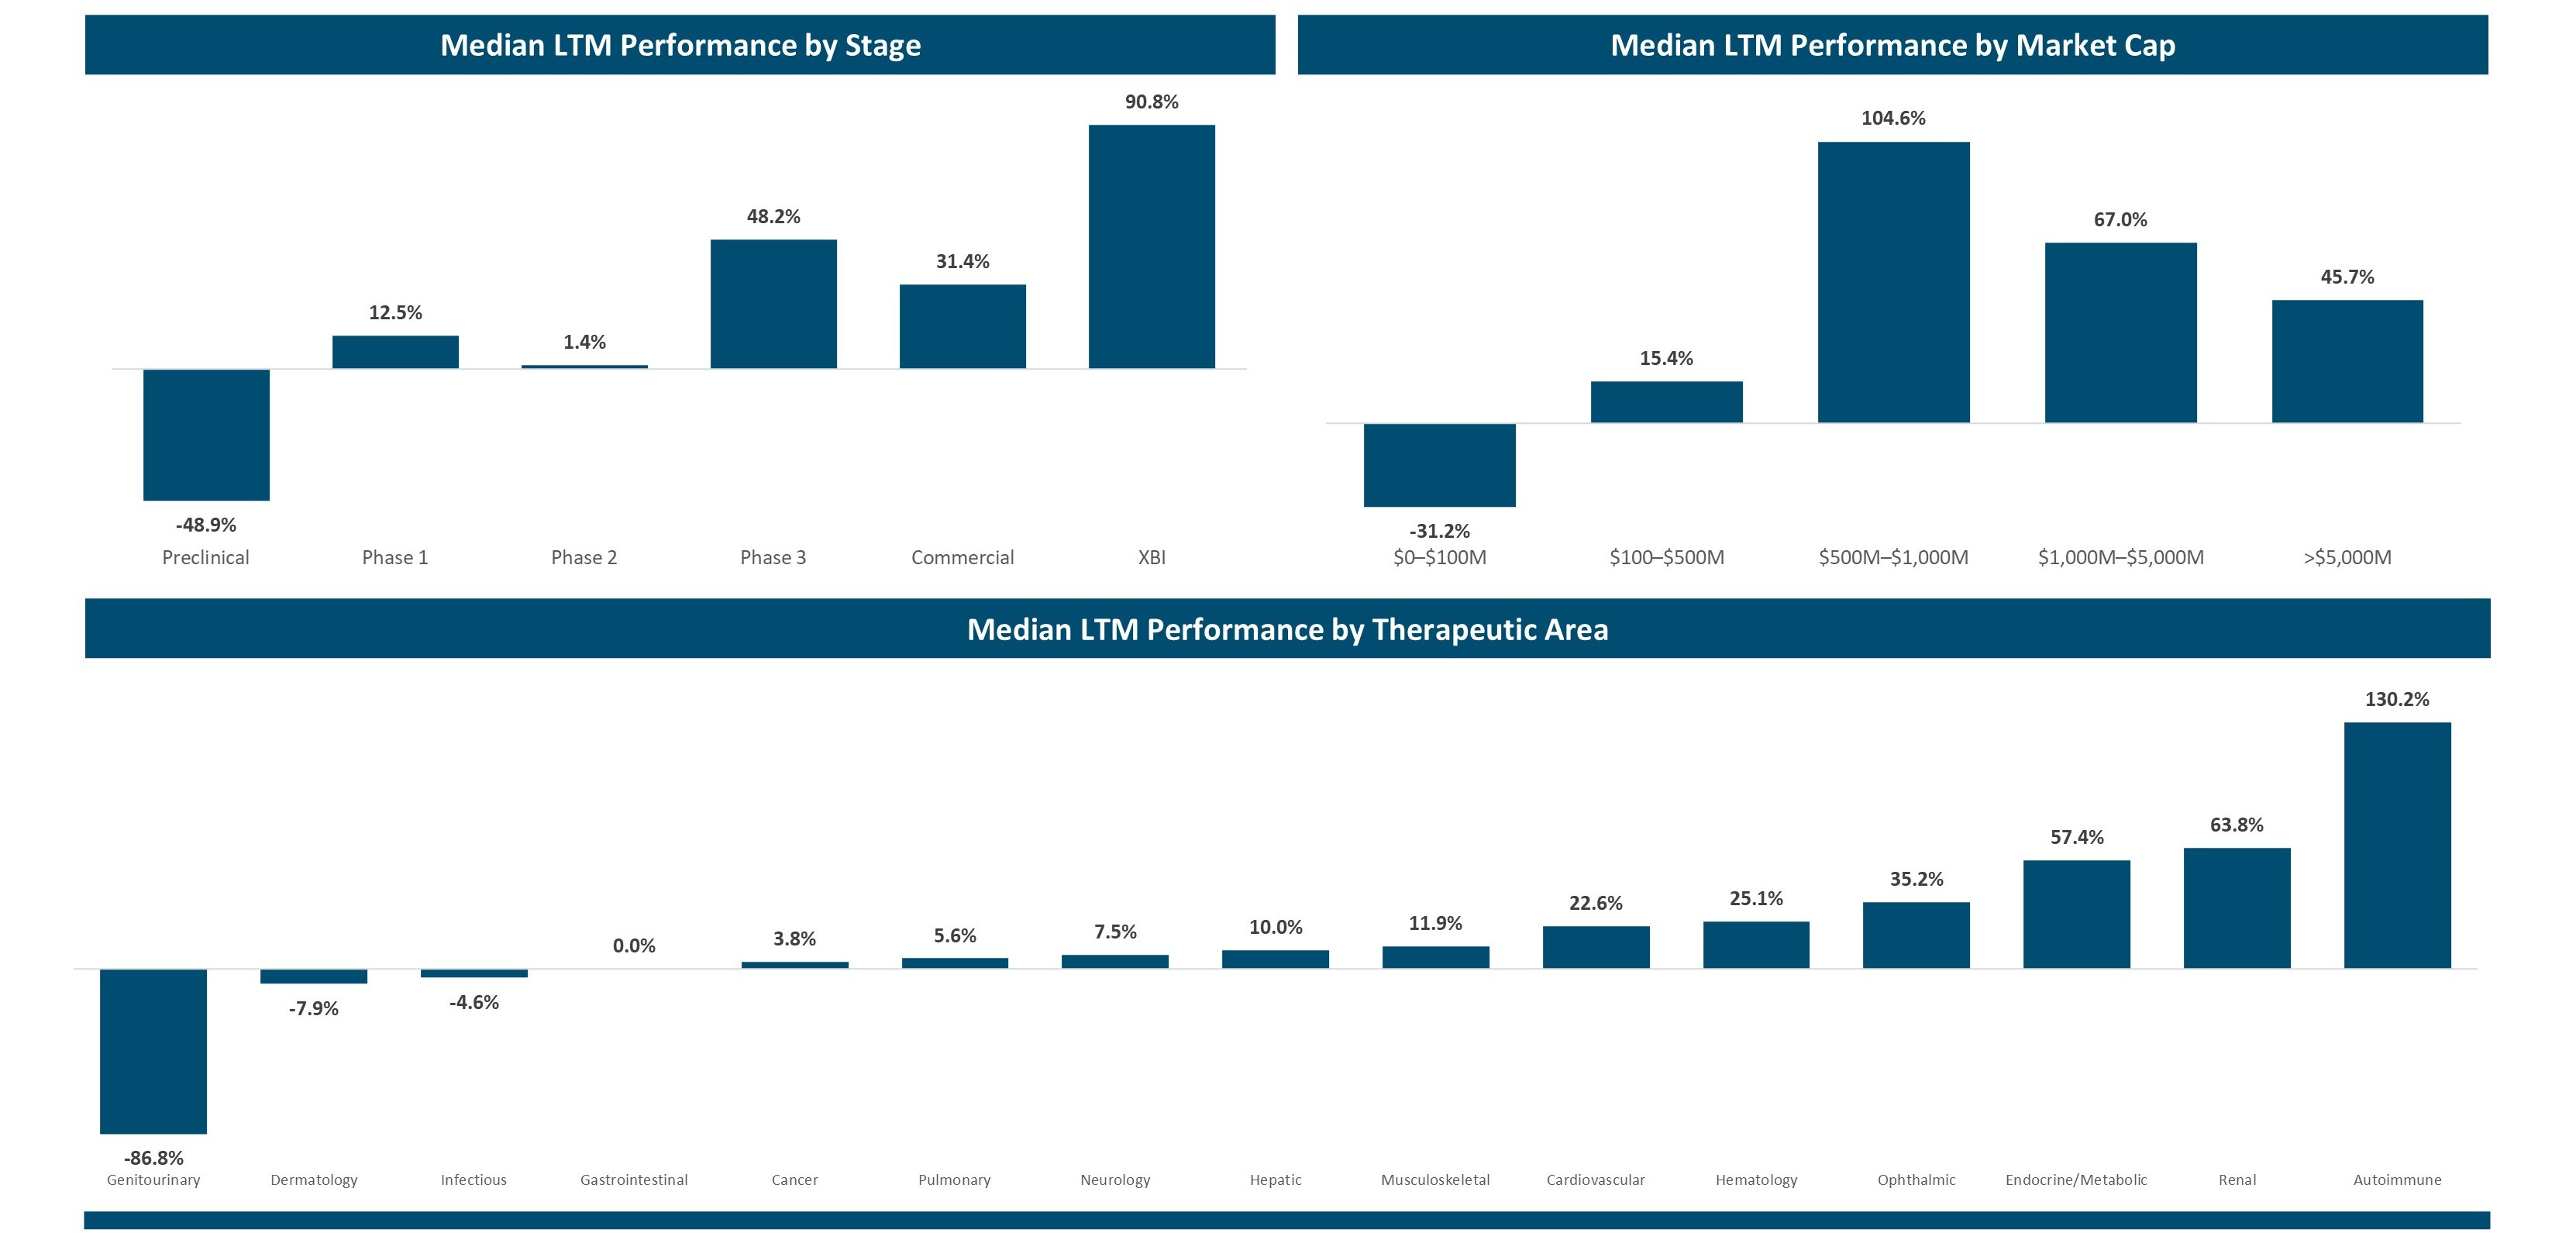
M&A — Pharma underwriting may move toward a barbell strategy: Buyers may increasingly favor either earlier-stage assets acquired at lower valuations or later-stage programs with substantially de-risked clinical profiles, while avoiding expensive assets with unresolved Phase III risk.
M&A — De-risked revenue may command a higher strategic premium: Phase III-validated, near-commercial, and revenue-generating assets could attract stronger demand, widening the valuation gap versus programs with unresolved translational or endpoint risk.
Competitive Markets — Product differentiation is becoming more important: As standards of care improve, clinical value is increasingly defined by relative efficacy, tolerability, dosing convenience, and treatment burden rather than efficacy versus placebo alone.
China — Strategic relevance continues to rise despite policy uncertainty: China is becoming a more structural part of global biotech R&D, licensing, and partnering, rather than simply a source of lower-cost assets.
Recent Venture Transactions
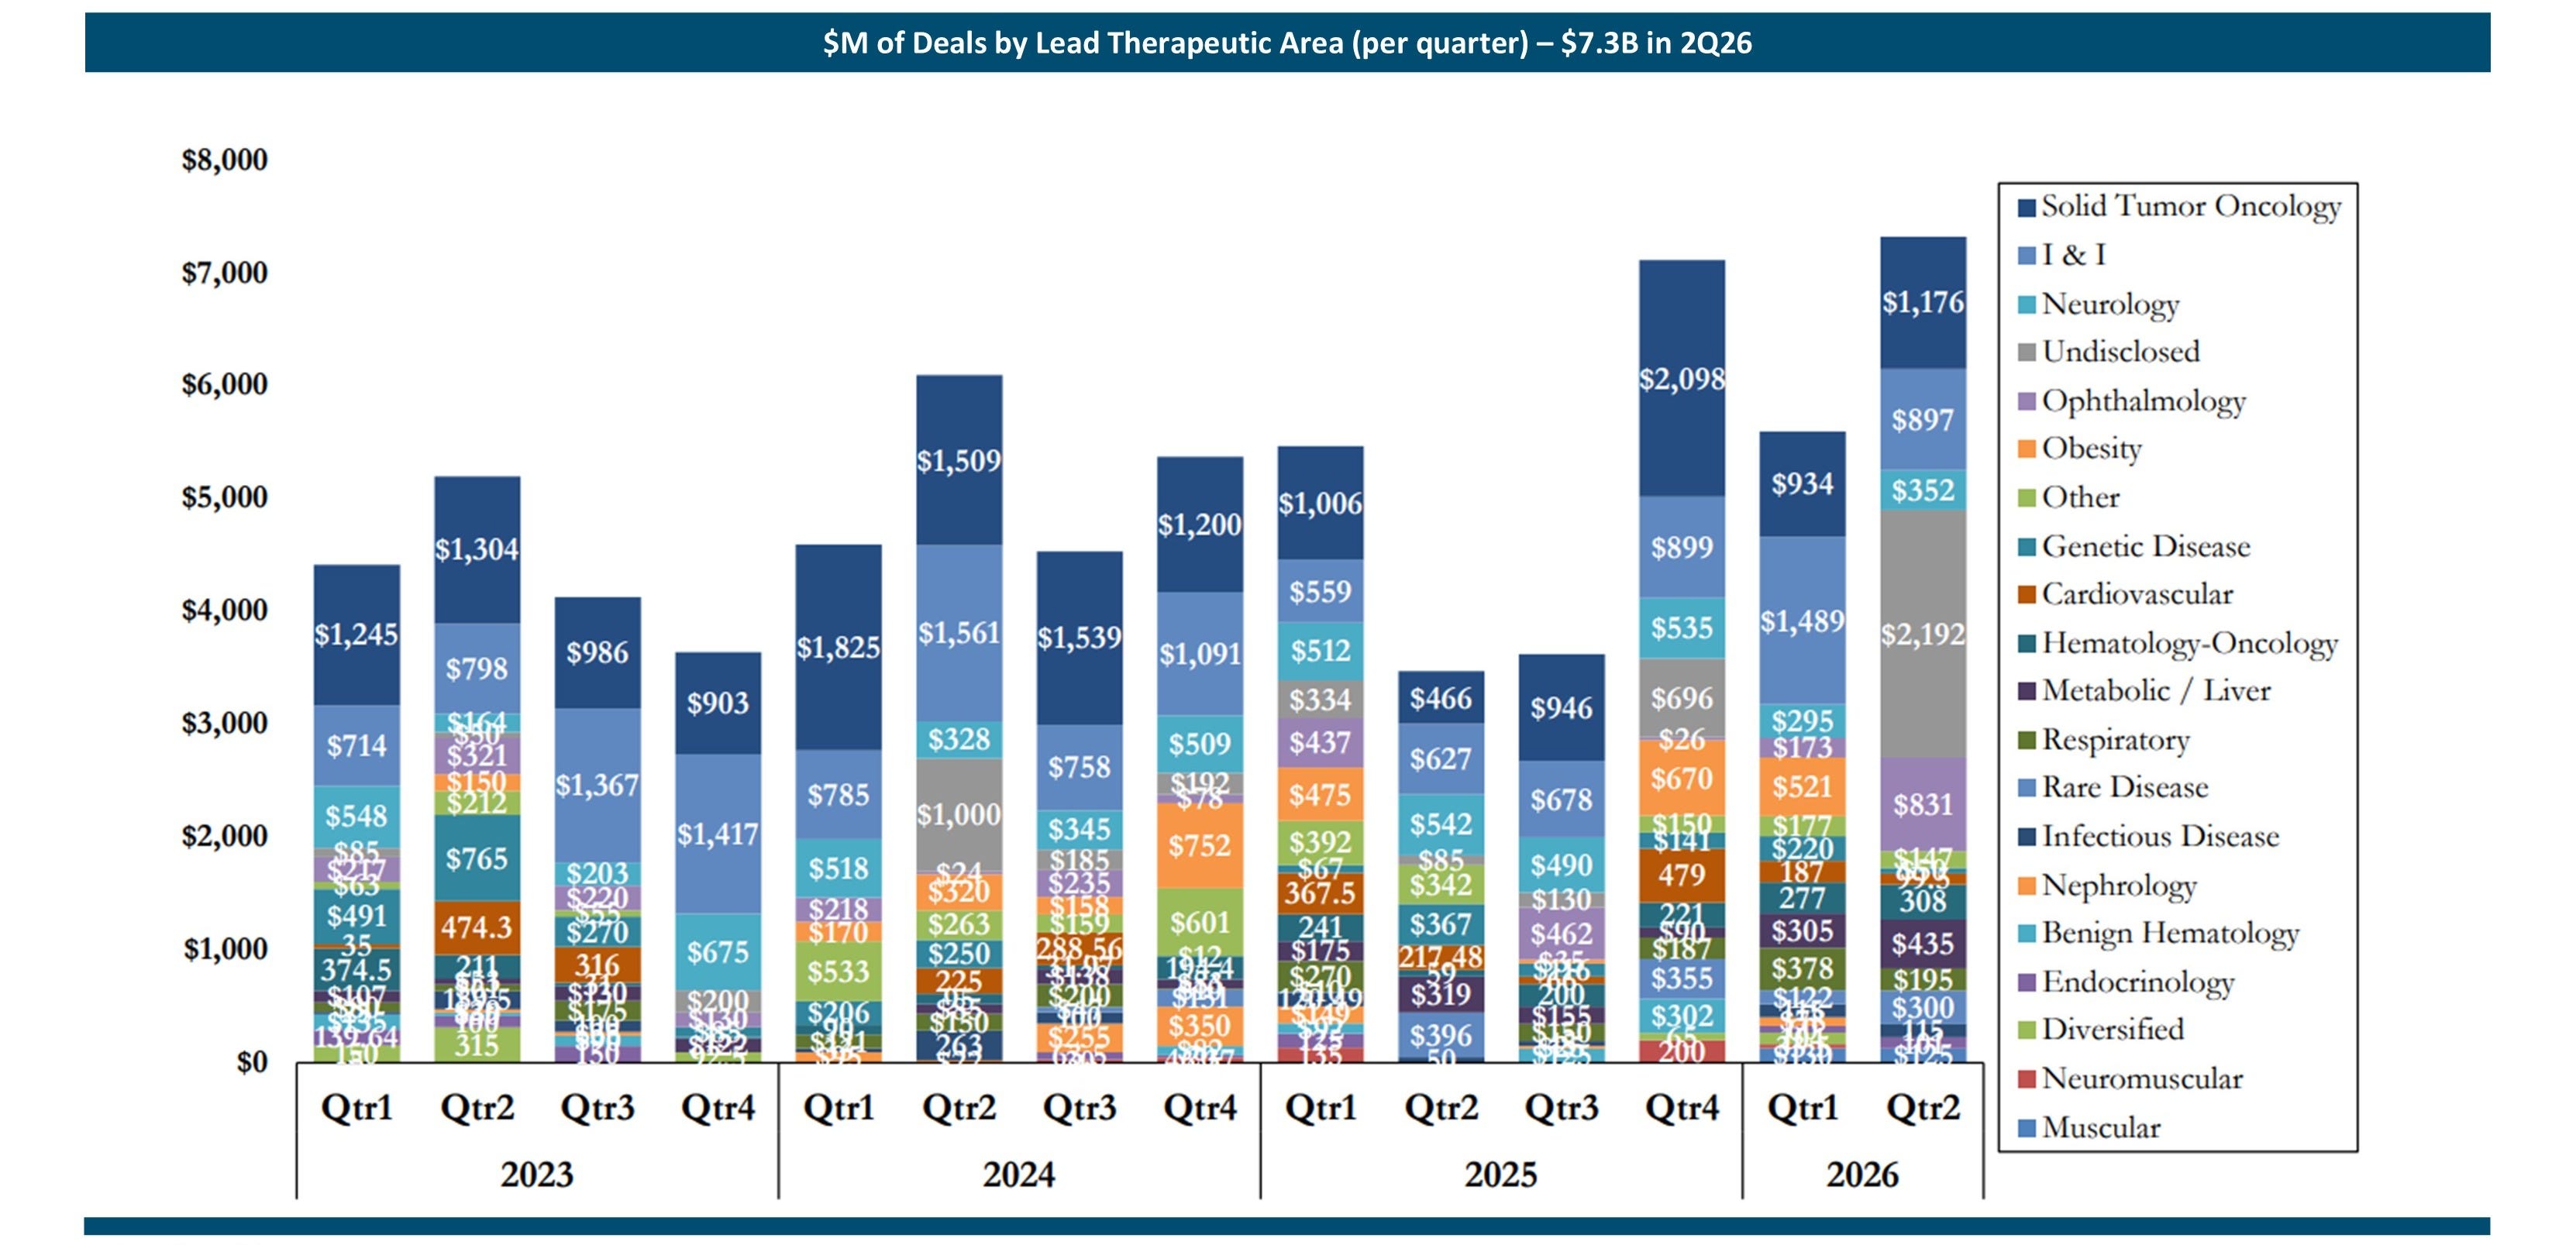
Healthcare venture activity is accelerating: 1H 2026 investment reached $31B across 1,101 deals, with Q2 representing the strongest quarter in the dataset and marking the best back-to-back quarterly performance of the current cycle.
Capital allocation remains barbelled: Investors are backing select early-stage companies while concentrating substantial capital into later-stage, momentum-driven rounds, even as first-time financings remain difficult.
Round structures are beginning to normalize: After the mega-round-heavy environment of 2024–2025, improving risk appetite and stronger M&A activity are supporting a partial return to more traditional round sizes and tighter syndicates, although capital remains concentrated in larger financings.
Biopharma continues to dominate healthcare venture: Biopharma captured 50% of healthcare venture dollars in 1H 2026, reinforcing its position as the largest recipient of healthcare venture capital.
Recent Biotech IPO Tracker
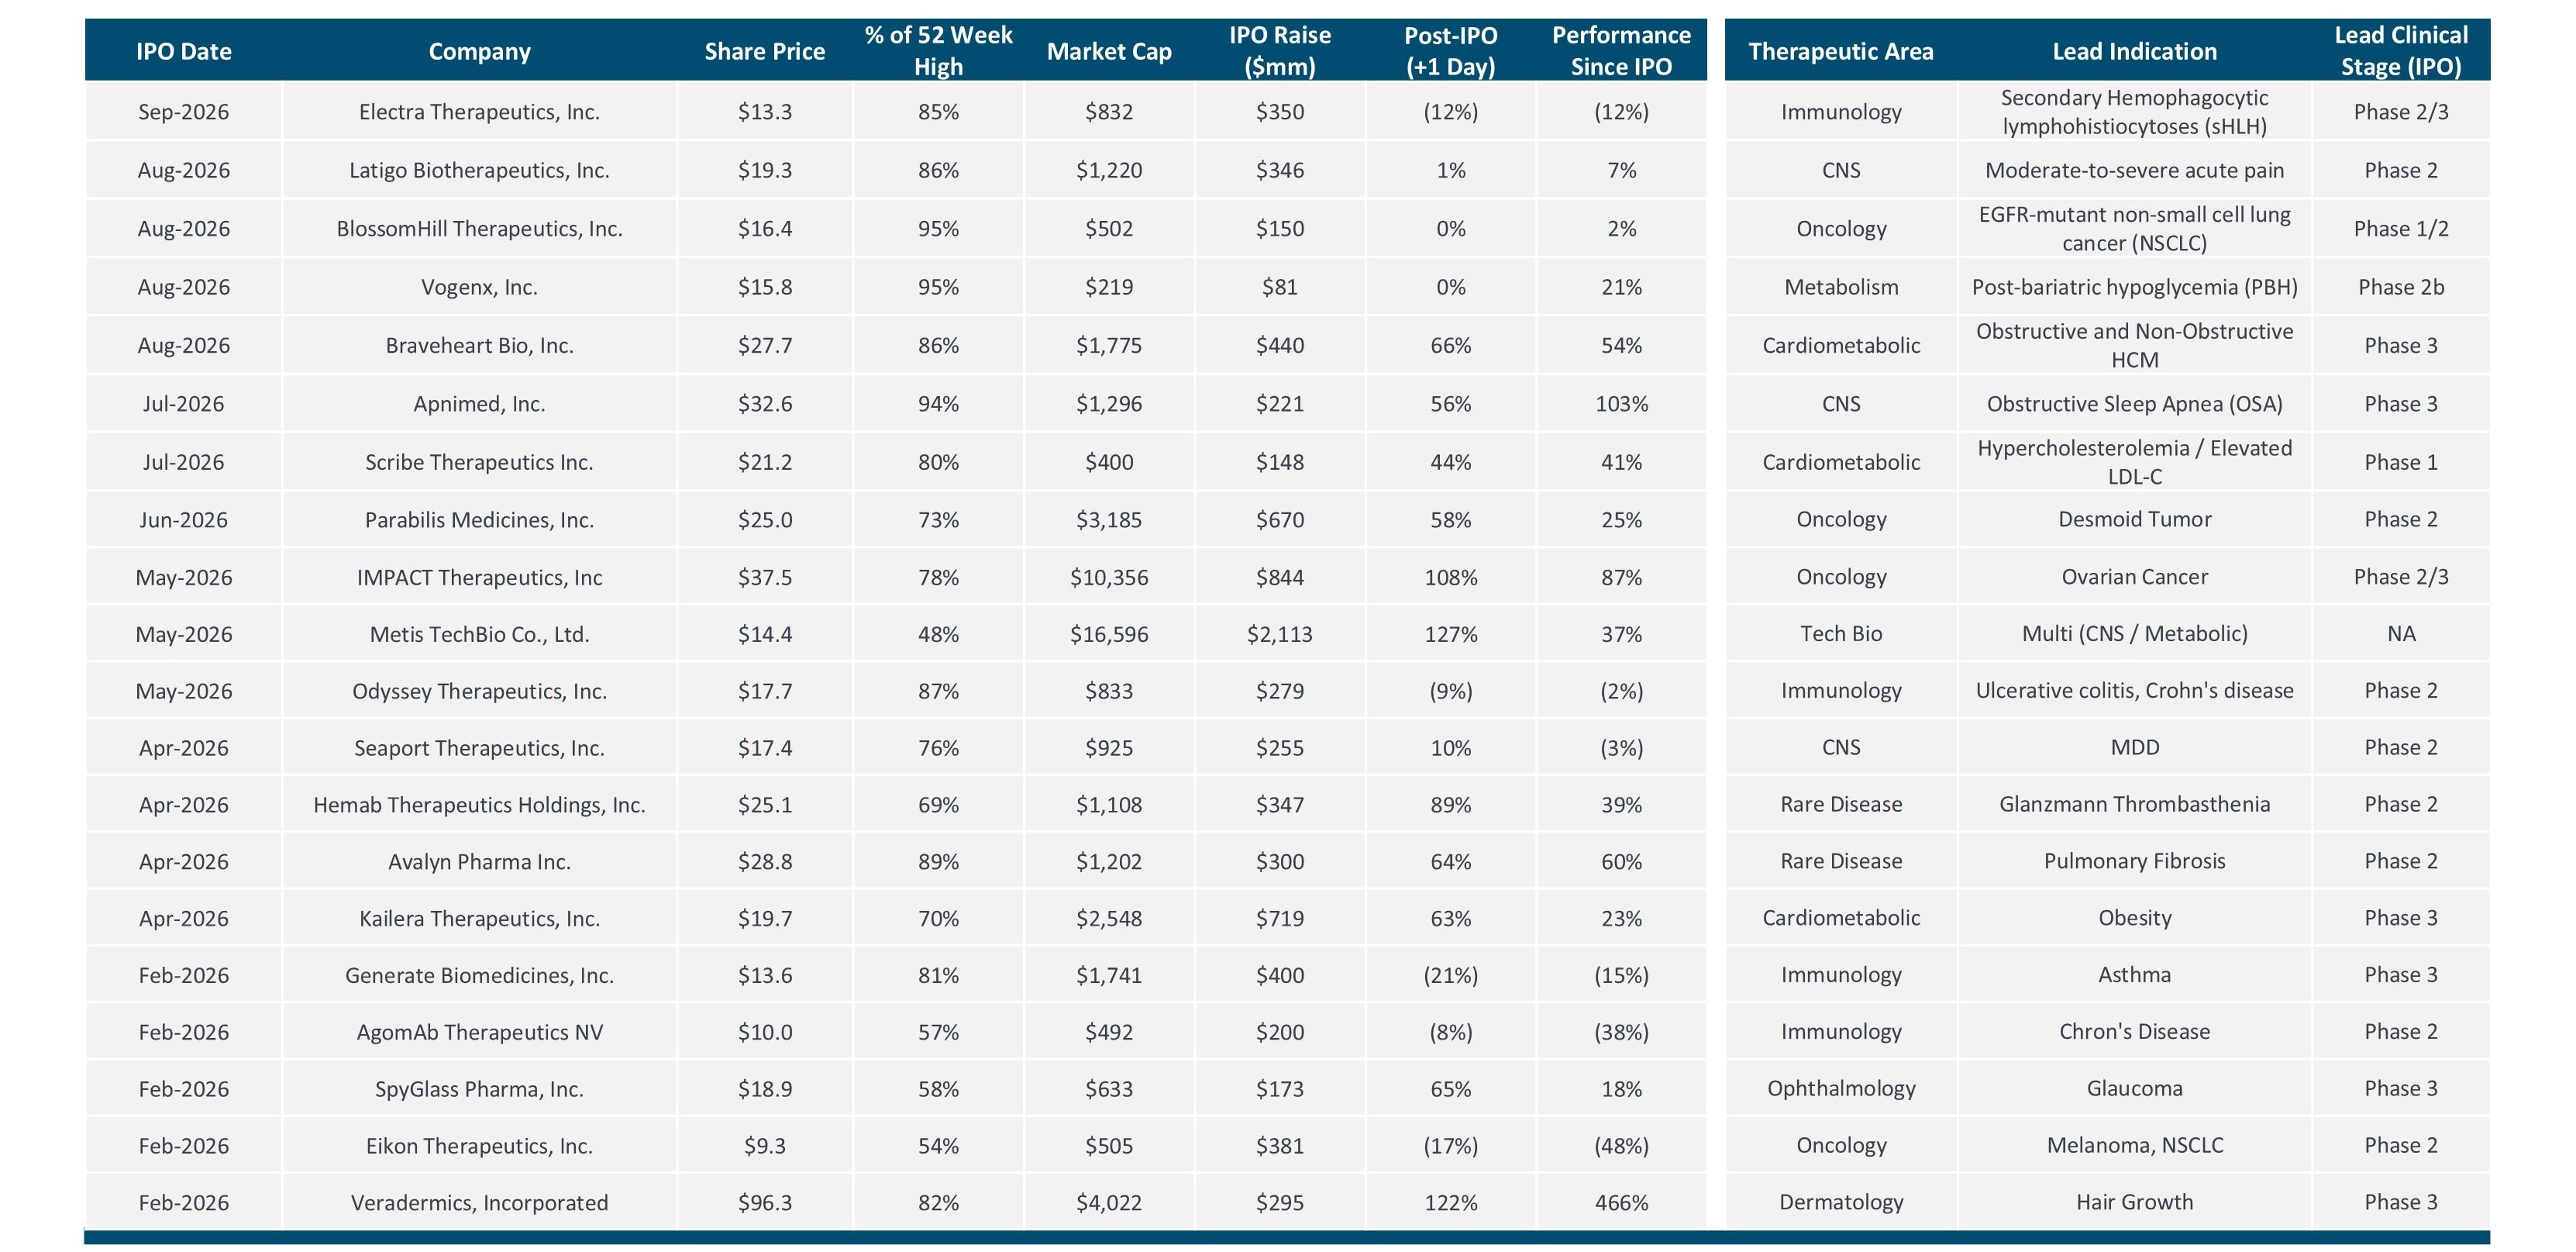
Please see the detailed report below:
