
Radiopharma CDMO
Radiopharmaceutical contract development and manufacturing organizations (CDMOs) are becoming critical infrastructure for nuclear medicine. The global market is projected to grow from $3.2 billion in 2025 to $7.5 billion by 2034, supported by increasing outsourcing and more than 260 active therapeutic trials. Growth remains constrained by isotope availability, qualified GMP capacity and specialist talent.
Market Scope
· Precursor & Isotope Supply: Enrichment and production of medical radioisotopes through reactors, accelerators and generators.
· Equipment & Manufacturing: Shielded infrastructure, radiolabeling, formulation, sterile fill-finish and quality control.
· Development & Clinical Services: Therapeutic development, trial execution, imaging, dosimetry and regulatory support.
· Distribution & Diagnostics: Patient-specific dose preparation, timely delivery and PET/SPECT imaging for patient selection and monitoring.
Market Trends
· Capacity Expansion: CDMOs are adding GMP facilities and broader manufacturing networks.
· Isotope Security: Long-term supply agreements and redundant sourcing are becoming competitive advantages.
· Alpha-Therapy Investment: Ac-225 and Pb-212 are attracting investment alongside established Lu-177 therapies.
· Vertical Integration: Companies are combining isotope production, manufacturing and distribution to reduce supply risk.
· Longer-Term Contracts: Technology-transfer fees, capacity reservations and multi-year agreements improve revenue visibility.
· Decay-Driven Geography: Short-lived isotopes favor production close to treatment centers.
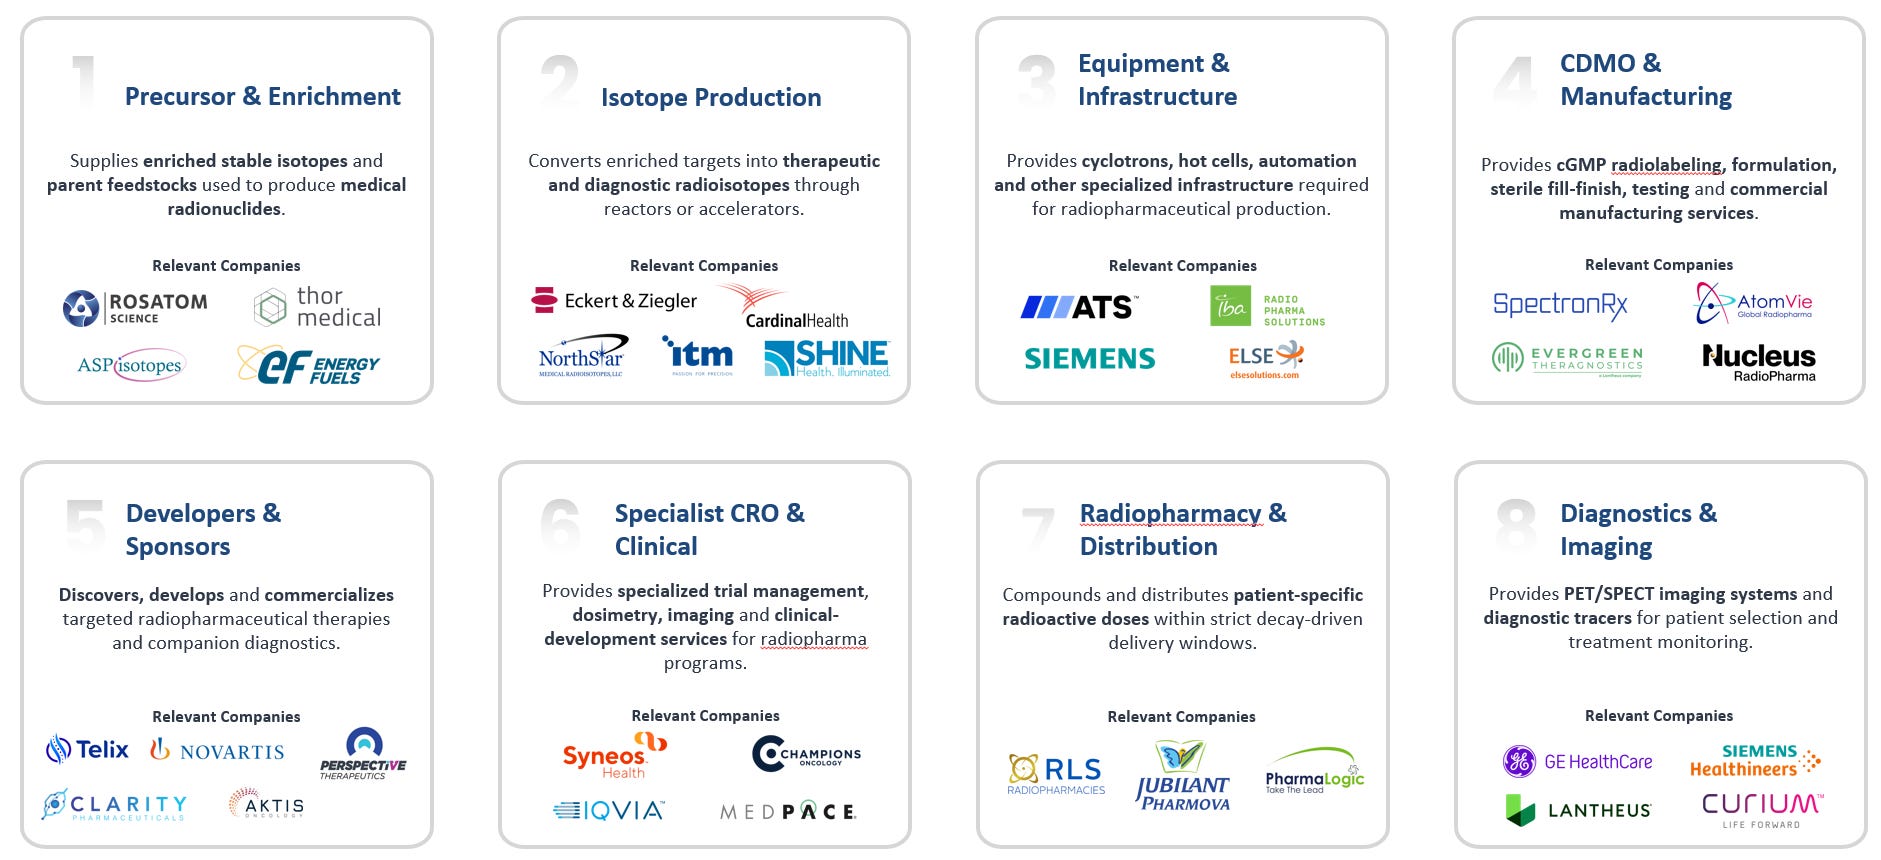
Radiopharma Industry Structure
Investor Considerations
Precursor & Enrichment: Secure feedstock and specialized enrichment capabilities create barriers to entry; concentrated supply adds geopolitical risk.
Isotope Production: High capital requirements make utilization and long-term contracts critical; emerging isotopes carry production and clinical risks.
Equipment & Infrastructure: Recurring service revenue supports earnings, while long production and installation cycles pressure cash flow.
CDMO & Manufacturing: Contracted utilization, take-or-pay agreements and regulatory compliance matter more than installed capacity alone.
Developers & Sponsors: Clinical maturity and approval prospects drive valuation; proprietary platforms can offer greater strategic value.
Specialist CRO & Clinical: Growing trial activity supports demand; software adds recurring revenue, while talent shortages constrain capacity.
Radiopharmacy & Distribution: Dense local networks create competitive advantages, but regional expansion requires substantial investment.
Diagnostics & Imaging: Reimbursement, commercial demand and reliable local distribution shape adoption and investment value.
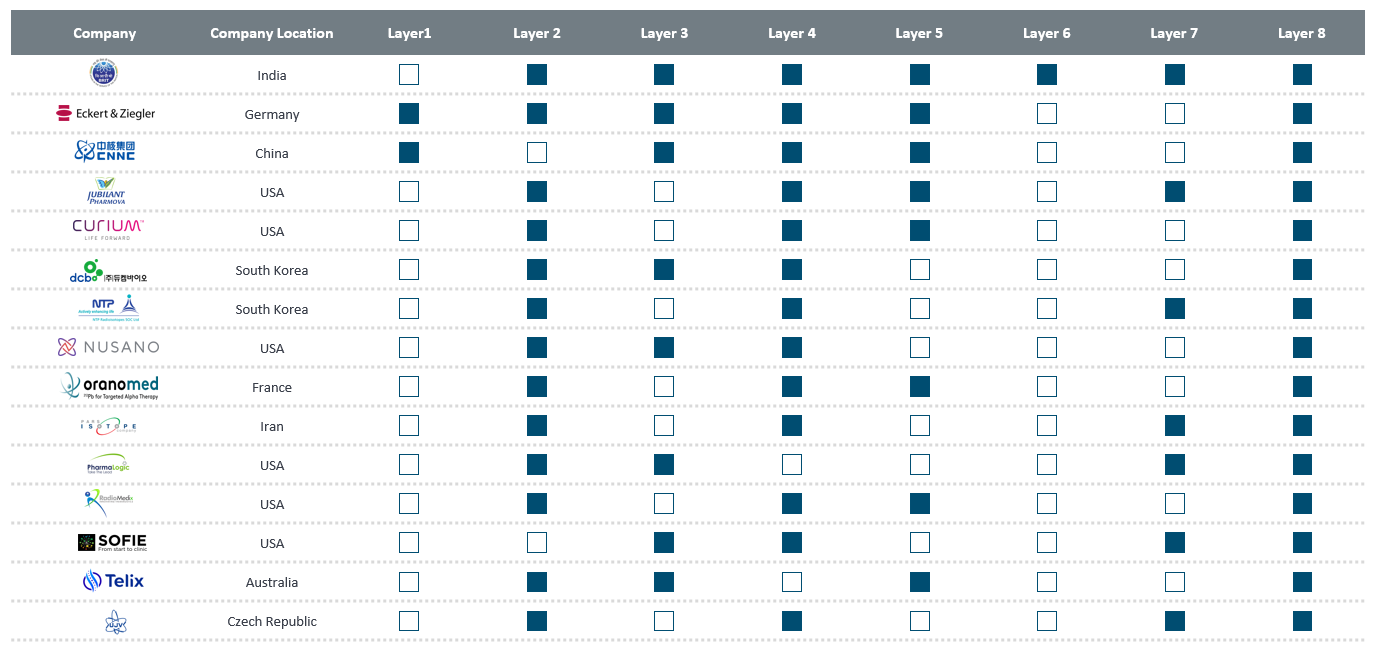
Integrated Platforms & Investor Positioning
Private Investor Insights
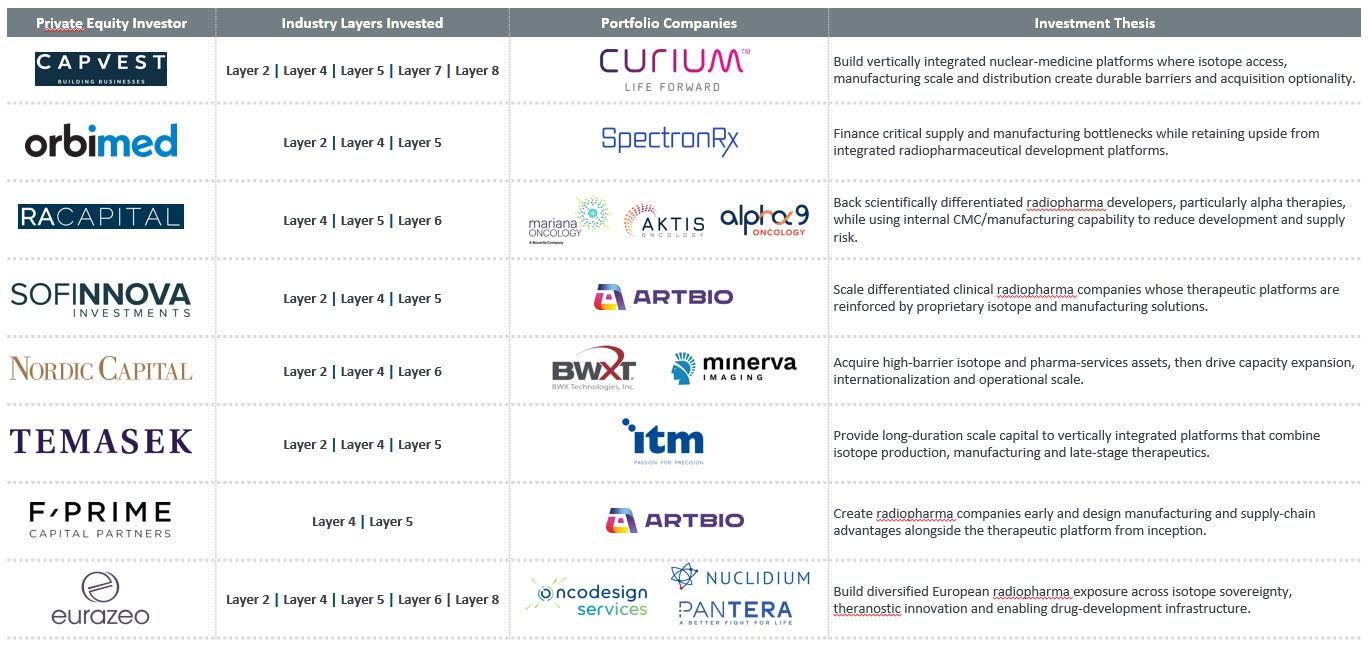
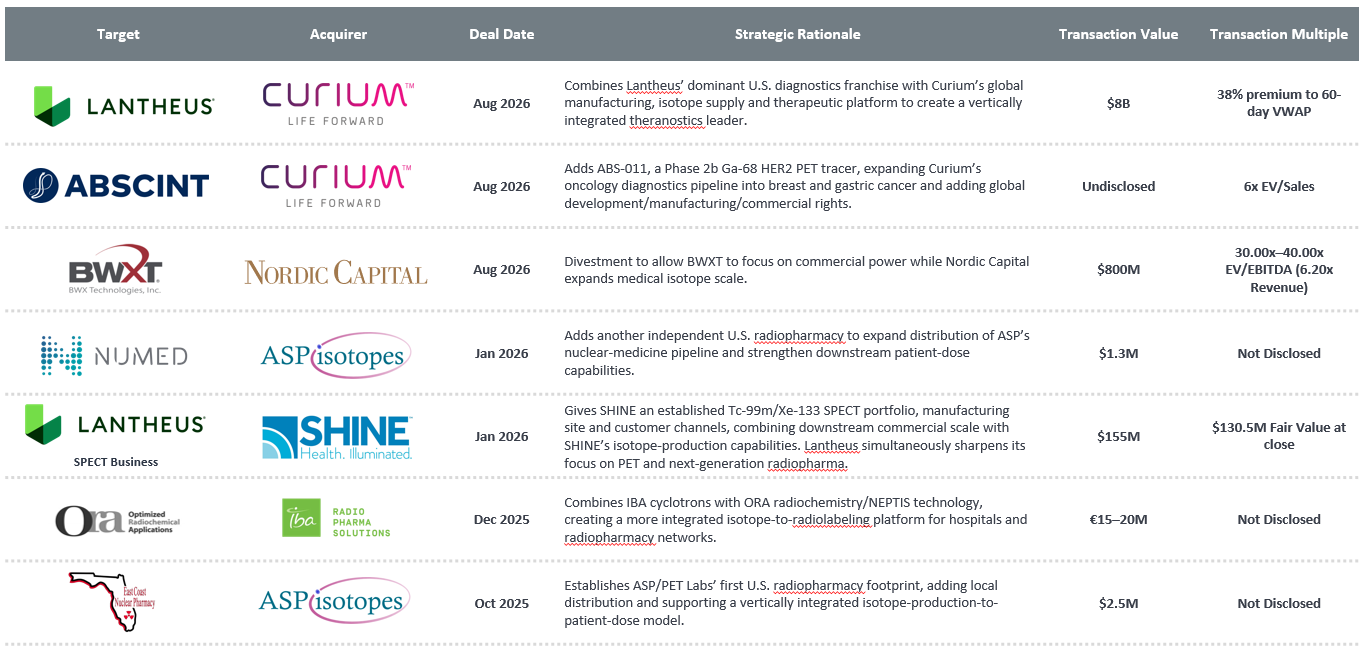
M&A & Platform Consolidation
See the Full Report Below
