
Transaction Highlights:

Key Takeaway
Vertical Integration: McKesson already has experience in clinical care delivery through its acquisition of US Oncology in 2010 and its Canadian INVIVA infusion network. The Option Care acquisition expands its presence in U.S. home and alternate-site infusion services.
Distribution vs. Care Delivery: Infusion services require nursing infrastructure, clinical operations, and patient access beyond pharmaceutical distribution. Execution risks remain in managing patient referrals and treatment administration.
Private Equity(PE) Opportunity: CD&R’s investment points to continued PE interest in established healthcare services companies trading at discounted valuations
Strategic Rationale - McKesson
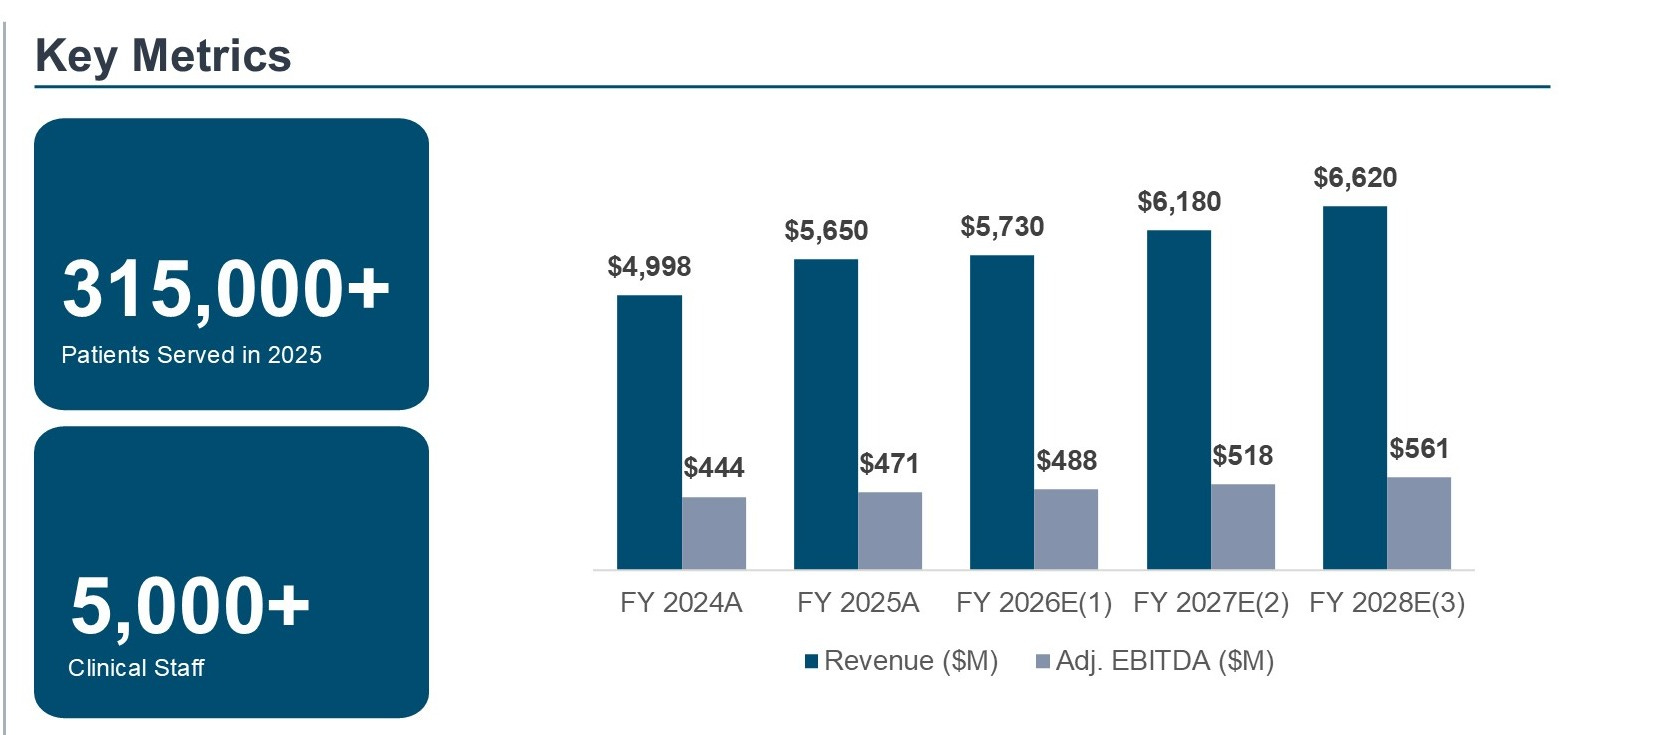
Expand Specialty Infusion Services: Gain access to a national home and alternate-site infusion network serving over 315,000 patients across all 50 states, supported by more than 5,000 clinicians and established hospital, physician, and payer relationships.
Broaden Specialty Care Capabilities: Expand into complex therapies for autoimmune, neurological, and rare diseases while supporting the shift from hospitals to lower-cost home and community-based care.
Capture Commercial Synergies: Leverage McKesson’s purchasing power, pharmaceutical distribution infrastructure, and manufacturer relationships to improve drug procurement and support new specialty therapies. Evercore estimates $1.0–$1.5B in potential incremental distribution revenue and $10–$30M in adjusted operating income.
Establish a Path to Full Ownership: Secure a framework to acquire CD&R’s remaining stake, subject to specified conditions and regulatory approvals.
Strategic Rationale – Option Care Health
Deliver value to shareholders: Offers $32.05 per share in cash, approximately 37% above the October 5 closing price. Provides a cash exit amid earnings pressure and uncertainty over the company’s recovery.
Continue under existing management: Keeps Option Care as a separate company with its own management team, with backing to invest in services and technology.
Expert Opinion on Transaction
J.P. Morgan — Attractive purchase price: Values the deal at 11× expected 2027 adjusted EBITDA, viewing the price as modest given Option Care’s strategic value.
William Blair — Recent problems explain the lower price: Notes that several similar home-based healthcare businesses sold at higher earnings multiples. Option Care’s patient losses and uncertain recovery help explain the difference. The buyers could benefit if the business improves.
Evercore — Earnings and distribution upside: Estimates a 0.7% boost to McKesson’s fiscal 2028 earnings per share before operating benefits, assuming an April 2027 closing. Additional distribution business could generate $1.0–$1.5 billion in revenue and $10–$30 million in adjusted operating income.
UBS — Limited early benefit: Expects McKesson’s first-year earnings to remain broadly unchanged or fall slightly before operating benefits, assuming 50% debt and 50% cash funding.
Option Care Health: Company Overview
Option Care Health (NASDAQ: OPCH) is the largest independent provider of home and alternate-site infusion services in the United States. The company provides specialty pharmaceutical therapies outside traditional hospital settings through an integrated network of pharmacies, infusion facilities, and more than 5,000 clinical professionals.
Business Model and Services
Chronic Therapies (~75% of Revenue): Recurring infusion treatments for autoimmune diseases, immune deficiencies, neurological conditions, and rare disorders.
Acute Therapies (~25% of Revenue): Short-term infusion treatments, primarily intravenous antibiotics for serious infections.
Integrated Care Delivery: Combines pharmaceutical procurement, medication preparation, nursing services, treatment administration, patient monitoring, and insurance authorization.
Reimbursement Model: Generates revenue through commercial insurers, government healthcare programs, and other payers under negotiated reimbursement arrangements.
Financial Performance
Competitive Positioning
National operating scale, established hospital and physician referral relationships, and specialized clinical infrastructure.
Its integrated pharmacy and nursing capabilities enable the administration of complex specialty therapies in patients’ homes and ambulatory infusion centers.
Benefits from growing specialty pharmaceutical utilization and the continued migration of clinically appropriate infusion treatments from hospitals to lower-cost care settings.
See the detailed Report Below: